DS4U research
2026-10-31
SAFPI October 2026: 57.7% of pay goes to debt
The full reading — monthly series, debt mix, income bands, the national context and the methodology.
Read the full analysis →SAFPI
Live first-party debt pressure data from real DS4U applications.
A monthly reading of how much of their income over-indebted South Africans already owe. Built from our applications and account-level bureau records, aggregated, and published with the sample size attached.
Latest SAFPI reading
57.7%
Typical share of net income already committed to debt repayments.
August – October 2026 · n = 1 213 applications
0.3 points on September's 58.0%
SAFPI trend
A higher percentage indicates greater financial pressure, with more of household income already committed to debt repayments.
Debt pressure
57.7%
of net income already committed to debt repayments.
August – October 2026 · n = 1 213
Debt mix
61.4%
Personal loans' share of unsecured balances.
August – October 2026 · n = 1 213
Debt review status confusion
49.9%
Unsure of their debt review status when applying.
August – October 2026 · n = 3 356
Among people approaching Debt Solutions 4U for debt review, the typical applicant is already committing R57.70 of every R100 of net income to unsecured debt repayments — before rent, transport, food and other living costs. That is the October 2026 reading of the South African Financial Pressure Index, measured across 1,213 debt review applications in the rolling August – October 2026 window. 55.7% of those applicants (676 of 1,213) commit more than half of their net income.
A closer look at the composition of unsecured debt in the October 2026 sample.
Unsecured debt mix (by balance)
Key insights from October 2026
| Debt type | Accounts | Share of accounts | Balance | Share of balance |
|---|---|---|---|---|
| Personal loans | 3,777 | 64.0% | R44.51m | 61.4% |
| Credit cards | 849 | 14.4% | R17.03m | 23.5% |
| Other | 313 | 5.3% | R5.08m | 7.0% |
| Store cards | 582 | 9.9% | R2.96m | 4.1% |
| Furniture accounts | 130 | 2.2% | R1.67m | 2.3% |
| Cellphone contracts | 242 | 4.1% | R0.91m | 1.3% |
| Student loans | 12 | 0.2% | R0.33m | 0.5% |
| Total | 5,905 | 100.0% | R72.49m | 100.0% |
Personal loans are the largest source of unsecured debt among people applying for debt review through DS4U. In the August – October 2026 SAFPI sample, personal loans were 61.4% of unsecured balances — R44.51 million of R72.49 million across 3,777 of 5,905 accounts. Store cards were numerous but small: 582 accounts carrying 4.1% of the balance.
Monthly medians move with the mix of who applies. The index itself is the rolling three-month figure, which is why it is the one to quote.
| Month | Median debt-to-income | Applications |
|---|---|---|
| January | 61.4% | 103 |
| February | 56.3% | 100 |
| March | 57.3% | 192 |
| April | 50.1% | 246 |
| May | 59.6% | 274 |
| June | 61.7% | 224 |
| July | 52.8% | 346 |
| August | 59.4% | 605 |
| September | 61.4% | 189 |
| October | 53.2% | 419 |
Every SAFPI reading published so far
| Reading | Published | SAFPI (rolling three months) | Applications |
|---|---|---|---|
| Baseline | 4 August 2026 | 57.8% | 616 |
| July 2026 | July 2026 | 57.6% | 843 |
| August 2026 | 31 August 2026 | 58.4% | 1,174 |
| September 2026 | 30 September 2026 | 58.0% | 1,139 |
| October 2026 | 31 October 2026 | 57.7% | 1,213 |
The October 2026 reading, in brief
SAFPI was 57.7% in the three months to October 2026, against 58.0% in the three months to September. A move of 0.3 points on 1,213 applications is within the range this series moves from one window to the next, so the reading is best described as unchanged. Every rolling reading published so far has fallen between 57.6% and 58.4%.
More than half of applicants, 55.7% (676 of 1,213), commit over half of their net income to unsecured debt repayments. Home loans, vehicle finance, rent and food all come after that.
Personal loans account for 3,777 of the 5,905 unsecured accounts in the sample (64.0%) and R44.51 million of the R72.49 million owed (61.4%). Credit cards are 14.4% of the accounts but 23.5% of the balance.
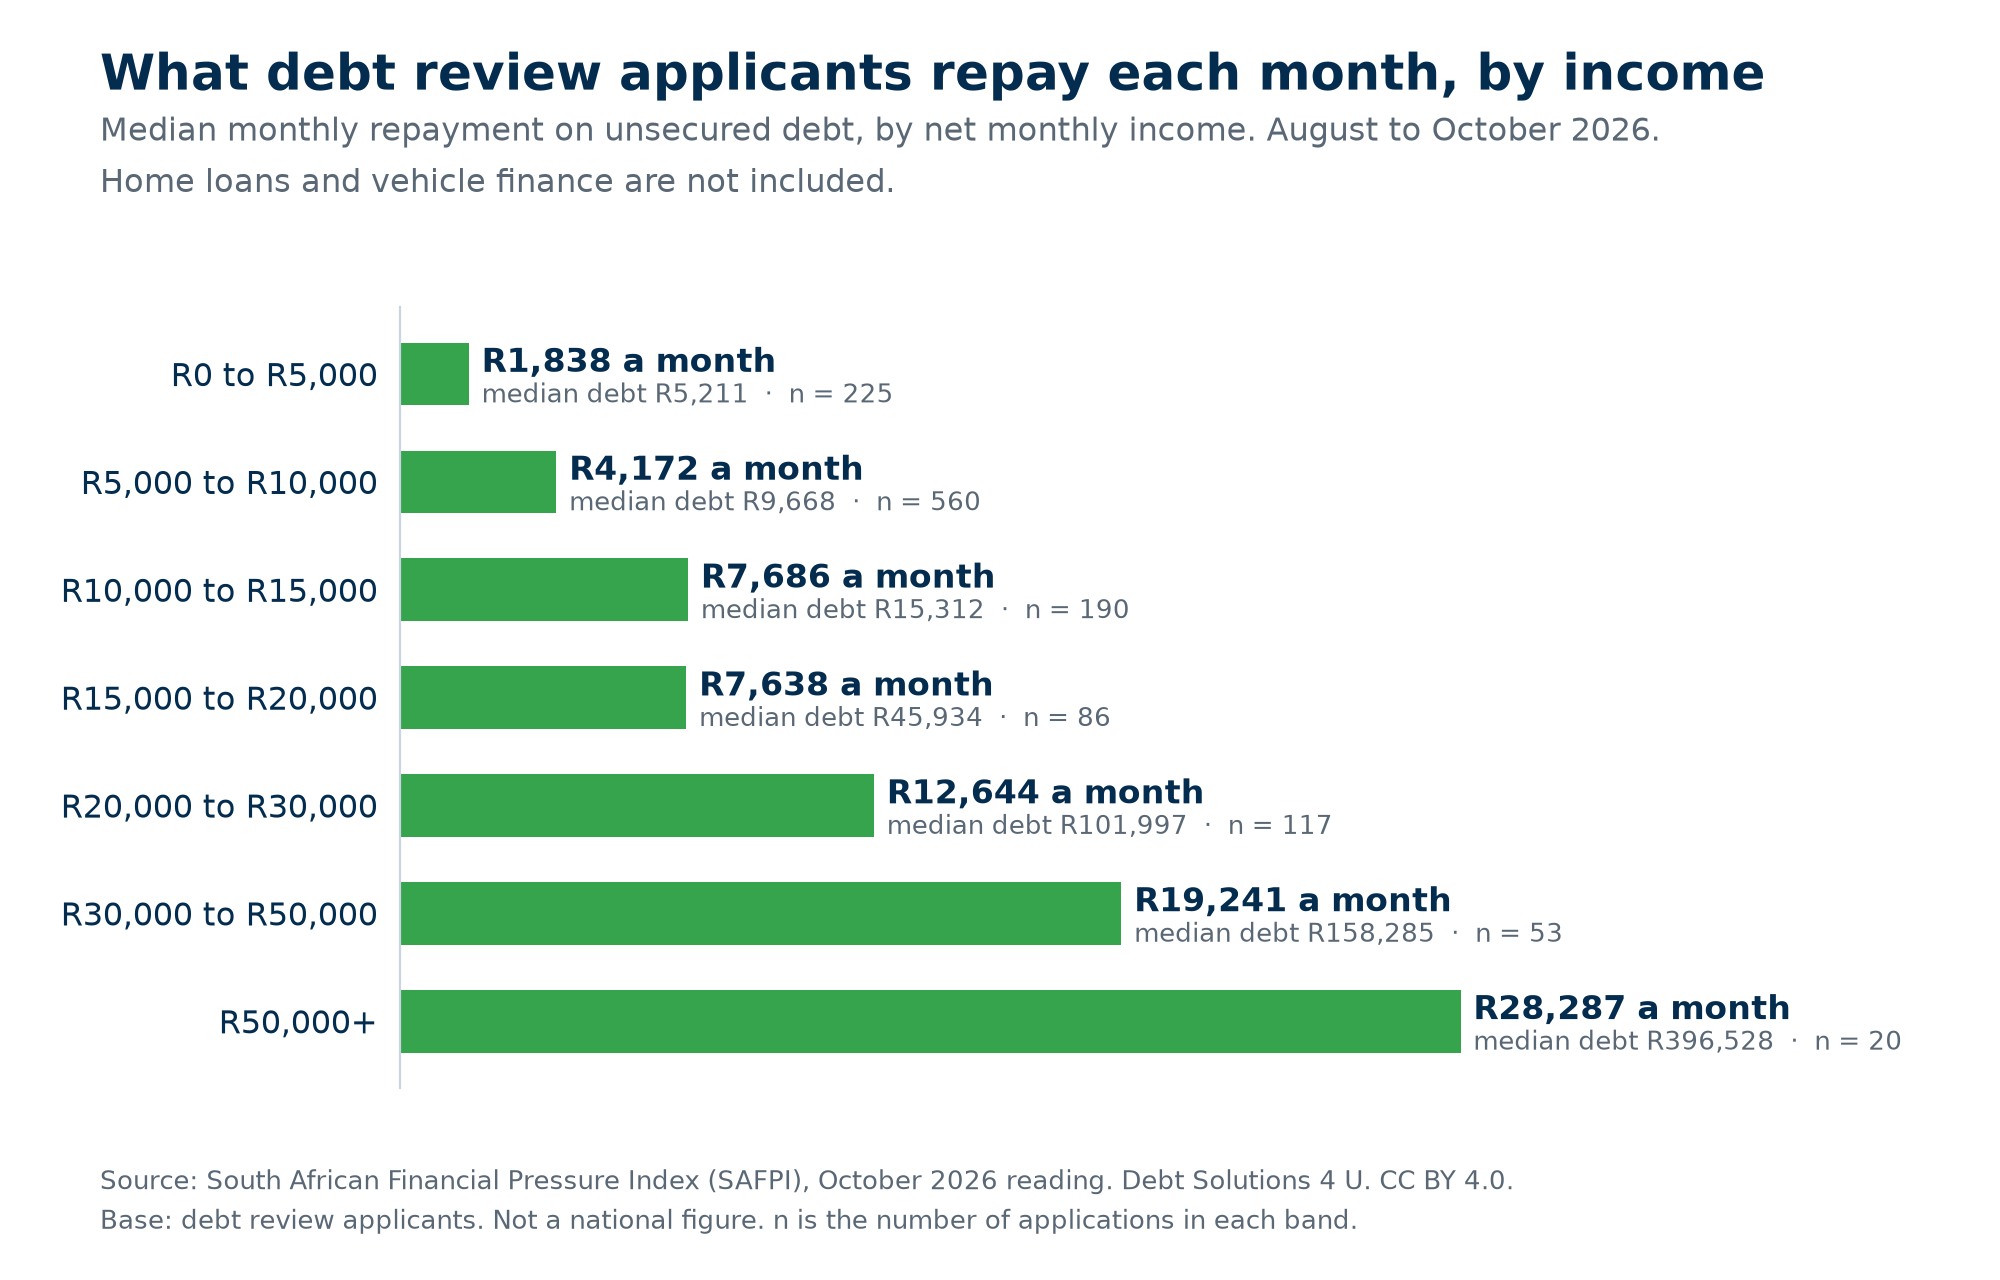
By number, the sample is mostly lower-income. Of the 1,251 applications in the income-band table, 560 (44.8%) came from people with a net income between R5,000 and R10,000 a month. Their median unsecured debt is R9,668 and their median repayment is R4,172 a month.
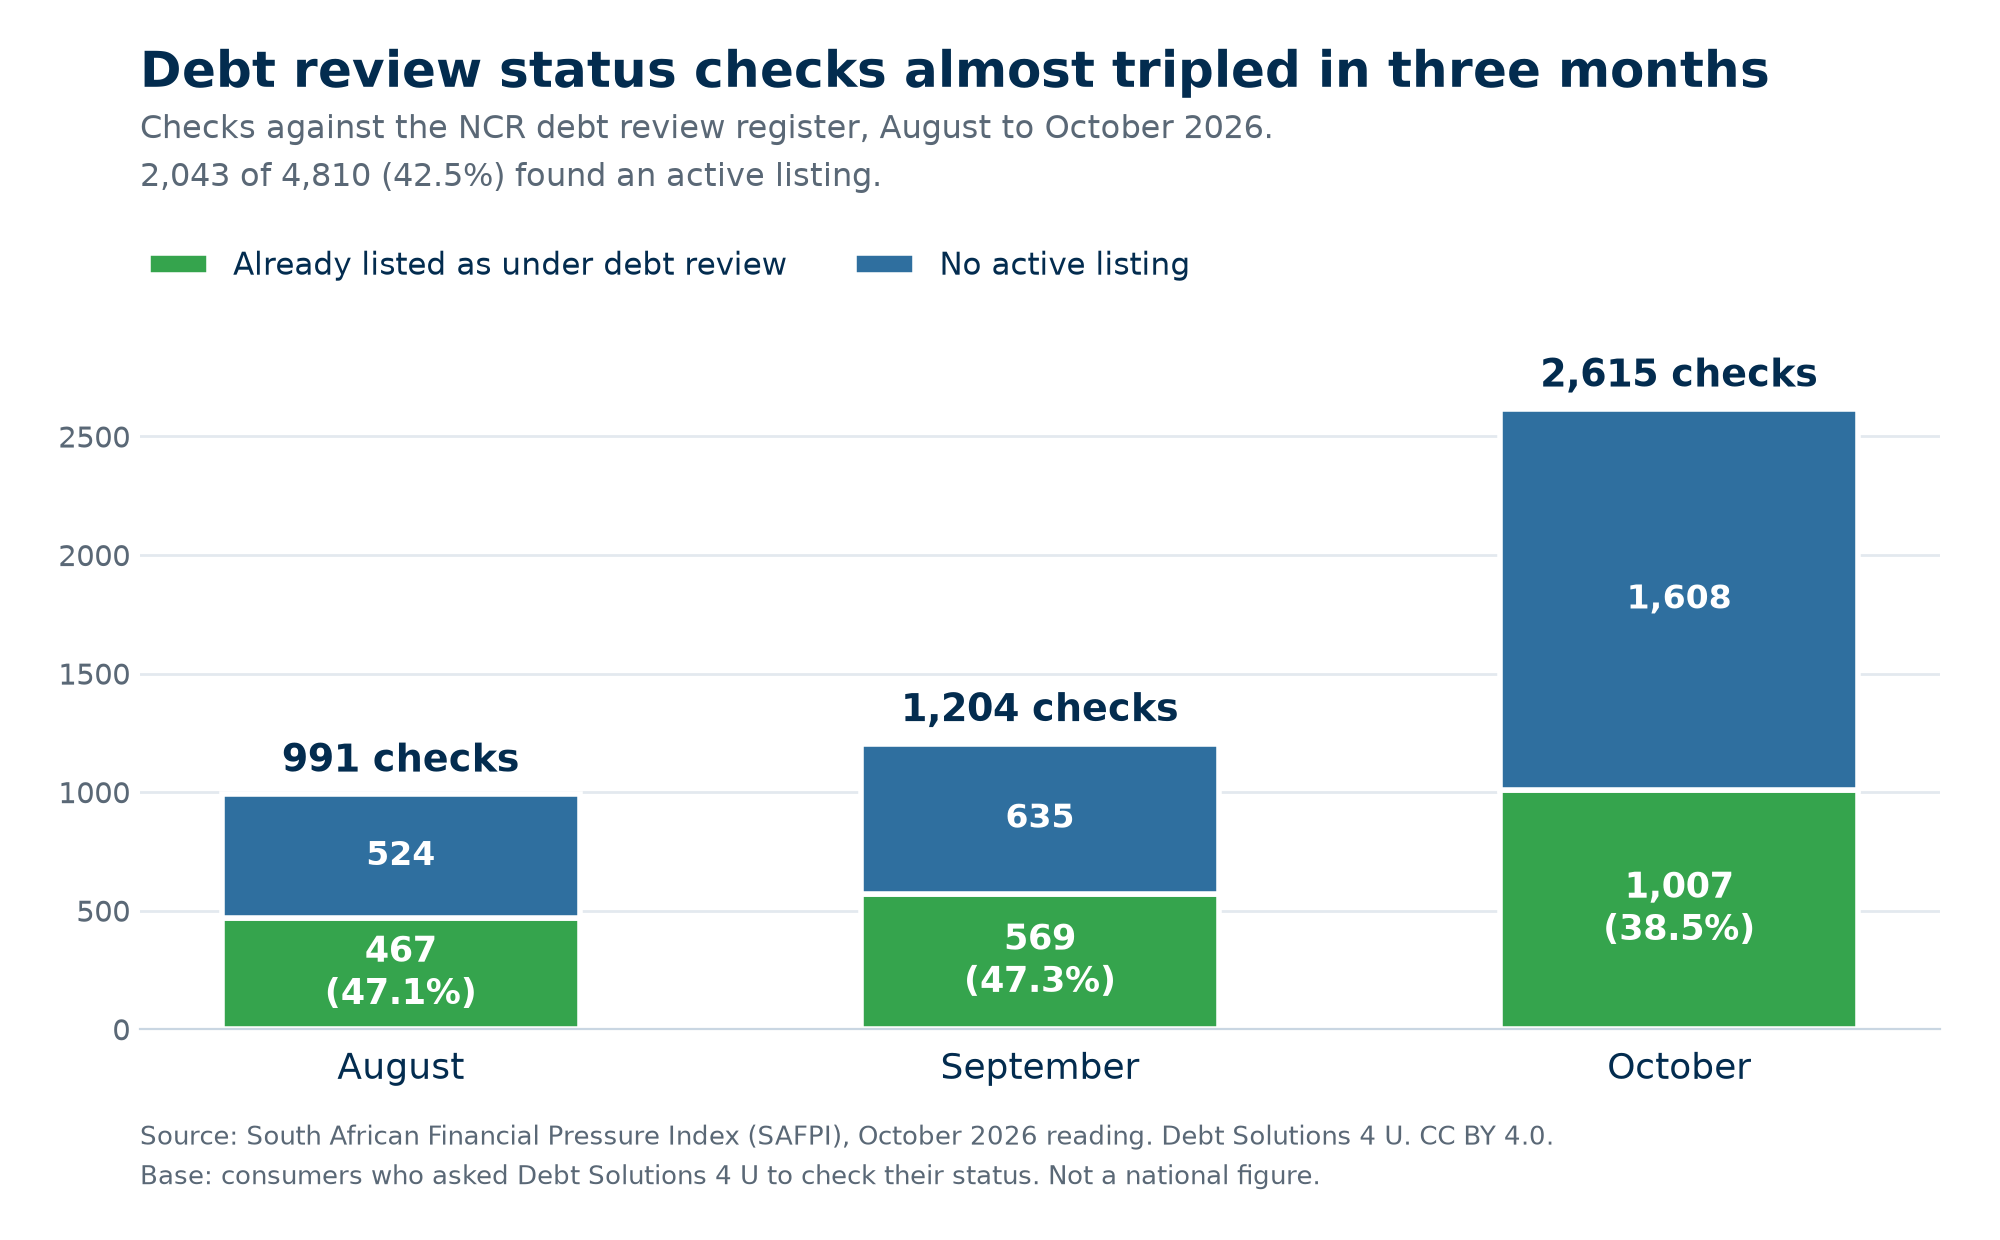
Requests to check a debt review status against the NCR register rose for a fourth month, to 2,615 in October from 1,204 in September. Across the 4,810 checks from August to October, 2,043 (42.5%) found the person already listed as under debt review. October's checks came from a wider group: 53.0% found no record on the register at all, against 39.5% in September, and the share already listed was 38.5%.
From 1 October, applications also come from DS4U's online debt review assessment, which asks applicants for their take-home pay and reads the same account-level bureau data. This issue includes 498 assessment records. October on its own reads 53.2% across 419 applications, the lowest single month since July. Single months move with who applies and are not the index; the next two readings will show whether the rolling figure follows October as August and September leave the window.
The window now includes October, the first full month after the Reserve Bank's rate increase took effect on 25 September.
September is shown as 189 applications at 61.4% in this issue, against 188 at 61.2% in the September issue.
Higher earners in this sample carry substantially larger unsecured balances.
Median monthly repayment on unsecured debt, by net monthly income, August to October 2026
Download the income band chart (PNG) Free to reproduce with attribution.
| Net monthly income | Applications (n) | Median unsecured debt | Median repayments | Median disposable |
|---|---|---|---|---|
| R0 – R5,000 | 225 | R5,211 | R1,838 | R1,000 |
| R5,000 – R10,000 | 560 | R9,668 | R4,172 | R3,576 |
| R10,000 – R15,000 | 190 | R15,312 | R7,686 | R6,220 |
| R15,000 – R20,000 | 86 | R45,934 | R7,638 | R9,005 |
| R20,000 – R30,000 | 117 | R101,997 | R12,644 | R12,755 |
| R30,000 – R50,000 | 53 | R158,285 | R19,241 | R19,913 |
| R50,000+ | 20 | R396,528 | R28,287 | R47,922 |
Debt review is not only a low-income problem. Among SAFPI applicants, higher-income households often carry substantially larger unsecured balances, because greater income also supports greater access to credit. Sample sizes in the upper bands are small and are printed beside every figure.
Largely, no. And this is the finding with a tool attached.
49.9%
were unsure of their status
1 676 of 3 356 applicants asked before their register check.
23.8%
of stated beliefs were wrong
Among the 1 680 people whose belief could be compared with the register.
2 615
register checks in October
Up from 1,204 in September. 42.5% of checks in the window found the person already listed.
NCR register checks by month, August to October 2026
Already under debt reviewNo active listing
991 checks · 47.1% already under debt review
1,204 checks · 47.3% already under debt review
2,615 checks · 38.5% already under debt review
Download the register checks chart (PNG) Free to reproduce with attribution.
| Month | Register checks | No listing found | Listed, since resolved | Already under debt review |
|---|---|---|---|---|
| August | 991 | 385 | 139 | 467 (47.1%) |
| September | 1,204 | 475 | 160 | 569 (47.3%) |
| October | 2,615 | 1,386 | 222 | 1,007 (38.5%) |
A credit report alone is not a reliable way to confirm whether you are currently under debt review. Of 3,356 SAFPI applicants asked before their register check, 1,676 (49.9%) said they were not sure; of the 1,680 who stated a belief that could be checked, 23.8% had it wrong. Across 4,810 register checks in the same window, 42.5% found the person already actively listed. DS4U checks the National Credit Regulator register when confirming a consumer's status.
Free. It does not affect your credit score.
DS4U research
2026-10-31
SAFPI October 2026: 57.7% of pay goes to debt
The full reading — monthly series, debt mix, income bands, the national context and the methodology.
Read the full analysis →IOL Business Reportexternal
29 September 2026
South Africans are among the world's most financially stressed
Third-party coverage of the SAFPI research.
Read on IOL Business Report →The Starexternal
12 August 2026
South Africans turn to credit as financial pressure builds
Third-party coverage of the SAFPI research.
Read on The Star →For journalists and researchers
Independent, real-world data on South African household debt pressure. Free to cite with attribution, with the methodology and the sample size published beside every reading.
Request the tablesFor consumers
Understand how other South Africans are managing debt, and what the data means for you. If it sounds like your month, we can help you work out whether debt review is the right next step.
How debt review worksEvery row names its source. Ours are labelled as ours.
| Indicator | Latest position | Source |
|---|---|---|
| Repo rate | 7.25%, raised 25bps on 23 September 2026 (effective 25 September). The second increase of 2026, after May's move to 7.0% | SARB MPC statement, September 2026 |
| Prime lending rate | 10.75%. Every prime-linked bond, vehicle loan and overdraft repriced upward again | SARB / banks |
| Consumer inflation | 4.5% in September 2026 (4.4% in August), published 21 October. The SARB's September statement expects it above 5% later in 2026 and early in 2027 | Stats SA / SARB |
| Household debt to disposable income | 61.3% in Q2 2026 (62.1% in Q1). Debt-service cost 9.4% of disposable income (9.5% in Q1) | SARB Quarterly Bulletin, September 2026 |
| Credit-active consumers | 29.24 million, of whom 10.54 million (36.05%) have impaired records. June 2025 quarter, the latest edition published | NCR Credit Bureau Monitor |
| Credit accounts at bureaus | 104.11 million accounts; 80.29% in good standing (June 2025 quarter) | NCR Credit Bureau Monitor |
| Accounts 3+ instalments behind | 14.6% of all accounts, with a further 4.4% carrying adverse listings (June 2025 quarter) | NCR Credit Bureau Monitor |
| Next rate decision | 19 November 2026 | SARB MPC |
12 placements carrying the research. Being reported on is not being endorsed — none of these outlets vouches for DS4U.
IOL Business Report
South Africans are among the world's most financially stressed
29 September 2026
The Star
South Africans turn to credit as financial pressure builds
12 August 2026
The Mercury
South Africans turn to credit as financial pressure builds
12 August 2026
DCASA
Earning More, Owing More: Why Debt Review Is Not a Low-Income Product
14 September 2026
The National
Why higher earners are falling into debt review in South Africa
10 September 2026
Scrolla
More Than Half Your Pay Could Already Be Going to Debt, and You Might Not Know It
11 September 2026
Rateweb
South Africans seeking debt help now hand over 58.4% of their pay — new Debt Pressure Index
1 September 2026 (updated 13 September 2026)
FAnews
The adviser impact of rising debt
8 September 2026
IOL
South Africans turn to credit as financial pressure builds
12 August 2026
Debtfree Magazine
Why Earning More Doesn't Always Mean Being Better Off
27 August 2026
The Citizen
A good salary is not protection against debt, report highlights
13 August 2026
Arcadia Finance
Index Says: Bigger Income Doesn't Mean Less Debt
15 August 2026
Population
Consumers applying for debt review through DS4U. Not a sample of South Africa.
Primary measure
Median percentage of net monthly income already committed to debt repayments.
Debt data
Account-level credit bureau records for the same applicants.
Income
Declared net monthly income, as submitted in the application.
Reporting window
Rolling three-month periods, with the sample size published beside every figure.
Minimum sample rule
Groups below n = 10 are reported as counts, never as a rate.
Limitations
SAFPI does not estimate the percentage of all South Africans who are over-indebted. Its population is consumers already seeking debt help, so it measures how deep the difficulty runs among people asking for help — not how many people are in difficulty.
Monthly medians move with the mix of applicants, not only with conditions: a month drawing more low-income applications reads differently from one drawing more high earners. That is why the index is the rolling three-month figure, and why every month is published with its n.
How to cite this
South African Financial Pressure Index (SAFPI), October 2026 reading. Debt Solutions 4 U. n = 1 213, August – October 2026.
Free to cite with attribution. Journalists and researchers can request the underlying aggregate tables and the sample composition; we do not supply client cases, and we do not supply figures we have not published.
Media & research enquiries
A named, NCR-registered debt counsellor is available for comment.
What is the South African Financial Pressure Index (SAFPI)?
SAFPI is a monthly index published by Debt Solutions 4U. It measures the median share of net monthly income that South Africans applying for debt review already commit to debt repayments, built from anonymised application data and account-level credit bureau records, and read alongside public data from the NCR, the Reserve Bank and Stats SA. The October 2026 reading is 57.7% (1,213 applications, rolling August to October 2026). The baseline reading, published in August 2026, was 57.8%.
Is SAFPI the same thing as the South African Debt Pressure Index?
Yes. SAFPI was briefly published under two names in 2026: the quarterly national report as the South African Debt Pressure Index (SADPI) and the monthly application series as SAFPI. From September 2026 they are one index under one name, the South African Financial Pressure Index (SAFPI), on this page. Any figure attributed to the South African Debt Pressure Index or SADPI in earlier coverage is a SAFPI figure.
What is the October 2026 SAFPI reading?
57.7%: the median share of net income that people applying for debt review already commit to debt repayments, measured across 1,213 applications in the rolling August to October 2026 window. That is down 0.3 points on the September 2026 reading of 58.0% (1,139 applications), and 55.7% of applicants (676 of 1,213) sit above a 50% debt-to-income ratio. October alone drew 419 applications; the largest single month in the series is August, with 605. The base is debt review applicants, not the country: SAFPI measures how deep the trouble is among people already seeking help.
How much of their income do South Africans spend on debt?
Among people applying for debt review, the median is 57.7% of net monthly income going to debt repayments before rent, transport or food (October 2026 reading). The Reserve Bank's national household debt-service ratio is 9.4% of disposable income (second quarter of 2026). Both are true: the national figure describes the whole country, SAFPI describes the households already in trouble.
What kind of debt puts South Africans into debt review?
Personal loans, by a wide margin. Across 5,905 unsecured accounts in the August to October 2026 window, personal loans were 3,777 accounts and R44.51 million of the R72.49 million owed, 61.4% of every rand. Credit cards were second at 23.5%. Store cards were numerous but small: 582 accounts carrying 4.1% of the balance. The baseline sample (7,393 accounts) showed the same pattern at 61.7%.
Do South Africans know whether they are under debt review?
Largely, no. Of 3,356 applicants asked before their NCR register check in the August to October 2026 window, 1,676 (49.9%) said they were not sure. Where a stated belief could be compared with the register (1,680 people), 23.8% had it wrong. Of the 4,810 register checks run in the window, 42.5% found the person already actively listed; in the baseline sample it was 44.1% of 524. Register checks through DS4U reached 2,615 in October, against 1,204 in September.
Which regions are under the most debt pressure in 2026?
Gauteng remains the highest-pressure province, with Johannesburg, Pretoria and the East Rand showing the strongest concentrations. Limpopo mining communities and Western Cape commuter regions also show elevated and worsening strain. Transport-dependent and mining-sector consumers remain among the most financially vulnerable segments.
What is driving the increase in debt pressure?
Two forces are compounding. Unsecured lending remains the structural driver: payday lending, app-based finance, retail credit, salary-backed lending and emergency cash loans covering monthly shortfalls. On top of that, the SARB has raised the repo rate twice in 2026, to 7% in May (its first hike since 2023) and to 7.25% on 23 September 2026, lifting prime to 10.75% and repricing every prime-linked bond, vehicle instalment and overdraft.
How is SAFPI compiled?
SAFPI combines DS4U's first-party data (debt review application medians, account-level credit bureau repayment data, NCR register checks and debt-help search demand across its national content footprint) with public regulatory and economic data (NCR Credit Bureau Monitor, SARB rate decisions, Stats SA inflation). Application figures are reported as medians with sample sizes, never as means, and always describe applicants rather than the national population. It is reviewed by an NCR-registered debt counsellor (NCRDC2423) and released under a CC BY 4.0 licence.
Should I check my debt review status before applying for help?
Yes, and it takes minutes. Because so many people running a check turn out to be actively listed, checking first tells you whether you need a fresh debt review application, a transfer to a new counsellor, or a clearance certificate because your restructured debts are already settled. You can check your status free with an NCR-registered debt counsellor before committing to anything.
Take control today
The index describes households already in difficulty. If it sounds like yours, speak to a registered debt counsellor and find out whether debt review could help.
Confidential · No obligation · NCR registered
Reviewed by Rowan Gary Breeds, NCR-registered debt counsellor NCRDC2423. Verify on the National Credit Regulator’s register. Reading published October 2026; figures as at August – October 2026. Data last updated 2026-11-02.
NCR RegisteredNCRDC2423
Your informationis secure
Thousands ofSouth Africans helped
As featured in leading South African publications
Coverage and independent mentions. Being featured is not an endorsement.